How to Claim Health Insurance – Required Documents and Step-by-Step Process
Health insurance can provide valuable financial protection when you need hospitalization or eligible medical treatment. However, having a policy is only one part of the process. Understanding how to claim health insurance is equally important because incorrect information, missing documents, delayed communication, or misunderstanding policy conditions can create difficulties during claim processing.
Health insurance claims are generally handled through two common methods: cashless claims and reimbursement claims. In a cashless claim, eligible expenses are settled directly with an eligible network hospital, subject to authorization and policy terms. In a reimbursement claim, the policyholder generally pays the hospital expenses first and later submits the required documents to the insurer or claims administrator for assessment.
The exact process, required documents, timelines, and conditions can vary depending on the insurer and policy.
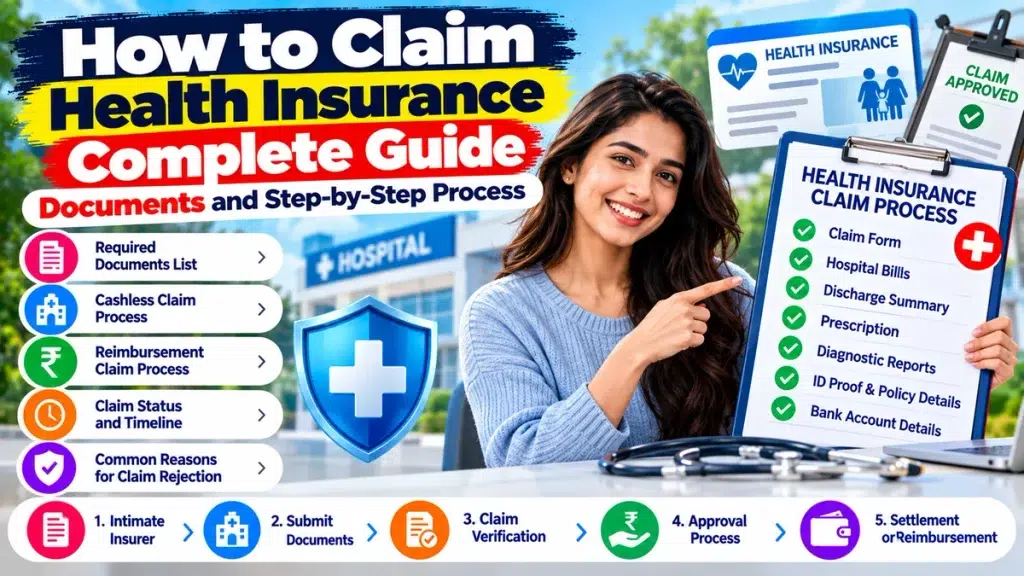
This complete guide explains the health insurance claim process, documents commonly required, cashless and reimbursement procedures, claim status, common reasons for claim issues, and important points to check before submitting a claim.
What Is a Health Insurance Claim?
A health insurance claim is a request made under an insurance policy for payment or reimbursement of eligible medical expenses.
When hospitalization or another covered treatment occurs, the policyholder or insured person can submit a claim according to the policy terms.
The insurer then assesses the claim based on factors such as:
- Policy validity
- Available sum insured
- Nature of treatment
- Medical necessity
- Waiting periods
- Exclusions
- Co-payment
- Deductibles
- Sub-limits
- Submitted medical documents
- Other applicable policy conditions
After assessment, the insurer may approve eligible expenses according to the policy terms, request additional information, or communicate another decision.
Types of Health Insurance Claims
Before starting the process, understand the two commonly used claim methods.
1. Cashless Health Insurance Claim
A cashless claim may be available when treatment is taken at an eligible hospital under the insurer’s applicable cashless arrangement.
Instead of paying all eligible hospital expenses and claiming them later, the hospital sends the required request and medical information for authorization.
If approved, eligible expenses are settled according to policy terms.
The insured may still need to pay non-covered expenses, deductibles, co-payments, or other amounts not payable under the policy.
2. Reimbursement Health Insurance Claim
In a reimbursement claim, the insured generally pays the hospital bill first.
After discharge, the policyholder submits the required documents and claim form to the insurer or claims administrator.
The claim is then reviewed.
If approved, eligible expenses are reimbursed according to policy terms, coverage limits, and applicable deductions.
Cashless vs Reimbursement Health Insurance Claim
| Feature | Cashless Claim | Reimbursement Claim |
|---|---|---|
| Hospital | Eligible cashless/network facility as applicable | Can depend on policy conditions |
| Initial Hospital Payment | Eligible approved expenses may be settled directly | Patient generally pays first |
| Pre-Authorization | Usually Required | Generally Not Used in the Same Way |
| Documents | Hospital and insured provide required information | Policyholder submits complete documents |
| Settlement | Eligible amount settled with hospital | Eligible amount reimbursed after assessment |
| Out-of-Pocket Payment | Non-payable expenses may remain | Initial hospital expenses generally paid by patient |
| Best Used For | Eligible cashless hospitalization | When cashless facility is unavailable/not used |
The exact process can differ between insurers, hospitals, and policies.
How to Claim Health Insurance – Step-by-Step Process
Although the procedure varies, the following steps provide a general overview.
Step 1: Check Whether Your Policy Is Active
Before initiating a claim, confirm that your health insurance policy is active for the relevant treatment date.
Review:
- Policy number
- Policy start date
- Policy expiry date
- Name of insured person
- Available coverage
- Sum insured
- Relevant waiting periods
- Co-payment or deductible conditions
An inactive or expired policy can affect claim eligibility.
Step 2: Check Whether the Treatment Is Covered
Not every medical treatment or expense is automatically covered.
Review the policy wording to understand whether the hospitalization, procedure, or treatment is eligible.
Also check:
- Exclusions
- Waiting periods
- Sub-limits
- Room-rent conditions
- Deductibles
- Co-payments
- Disease-specific conditions
This can help you estimate what may or may not be payable.
Step 3: Inform the Insurer or Claims Administrator
Claim intimation is an important part of the process.
For planned hospitalization, contact the insurer or claims administrator before admission according to the policy’s required timeline.
For emergency hospitalization, notification may need to be provided within the timeline specified in your policy.
Use official communication channels provided by the insurer.
Keep any acknowledgement, reference number, email, SMS, or claim ID received.
Cashless Health Insurance Claim Process
Cashless claims can reduce the need to arrange the entire eligible hospital expense upfront.
Step 1: Check Cashless Hospital Availability
Before planned hospitalization, check whether the hospital is eligible for the applicable cashless facility under your policy.
Hospital arrangements can change, so verify the current status rather than relying on an old hospital list.
Step 2: Contact the Hospital Insurance Desk
At admission, inform the hospital’s insurance or TPA desk that you want to use health insurance.
Provide the required policy and identity information.
Step 3: Submit the Pre-Authorization Request
The hospital generally prepares a pre-authorization request containing medical and treatment information.
This may include:
- Patient details
- Diagnosis
- Proposed treatment
- Doctor’s recommendation
- Estimated hospital cost
- Expected duration of hospitalization
The request is sent for review.
Step 4: Wait for Authorization
The insurer or claims administrator evaluates the information.
Additional medical information may be requested if required.
Authorization is subject to policy terms and does not necessarily mean that every final hospital expense will be payable.
Step 5: Receive Treatment
After applicable authorization, treatment can proceed under the cashless arrangement.
During hospitalization, additional authorization may sometimes be required if the treatment plan or estimated cost changes.
Step 6: Final Claim Assessment at Discharge
At discharge, the hospital submits the final bill and relevant medical information.
Eligible expenses are assessed according to policy conditions.
Step 7: Pay Non-Covered Expenses
The insured may need to pay expenses that are not covered.
These can potentially include:
- Non-payable items
- Applicable deductibles
- Co-payment
- Expenses above specified limits
- Excluded items
- Other charges not admissible under the policy
After completing the required formalities, the patient can be discharged.
Reimbursement Health Insurance Claim Process
If cashless treatment is not used or available, reimbursement may be an option subject to policy conditions.
Step 1: Inform the Insurer
Notify the insurer or claims administrator according to the required timeline.
Obtain a claim reference number if provided.
Step 2: Receive Treatment
Under the reimbursement method, the insured generally pays the hospital and other eligible medical expenses directly.
Step 3: Collect All Documents
Before leaving the hospital, collect the complete set of medical and billing documents.
Missing documents can delay assessment.
Step 4: Complete the Claim Form
Fill out the required claim form carefully.
Provide accurate details about:
- Insured person
- Policy
- Hospital
- Diagnosis
- Treatment
- Admission and discharge
- Claim amount
- Bank details where required
Do not provide incorrect or incomplete information.
Step 5: Submit the Claim
Submit the claim form and supporting documents through the insurer’s permitted channel.
Depending on the insurer, submission options may include online claim portals, apps, email, physical submission, or other approved methods.
Step 6: Respond to Additional Information Requests
The insurer may ask for additional documents or clarification.
Respond within the applicable timeline.
Step 7: Claim Assessment and Settlement
The insurer evaluates the claim against the policy terms.
If the claim is approved, the eligible amount is processed according to the insurer’s procedure.
The approved amount may differ from the total hospital bill because some expenses may be excluded or subject to limits, deductibles, or co-payment.
Documents Required for a Health Insurance Claim
Requirements vary depending on the claim, but commonly requested documents can include:
| Document | Purpose |
|---|---|
| Claim Form | Provides claim information |
| Policy Details | Identifies insurance coverage |
| Identity Information | Confirms insured person’s identity |
| Hospital Discharge Summary | Provides hospitalization and treatment details |
| Final Hospital Bill | Shows total hospital charges |
| Payment Receipts | Evidence of payments made |
| Itemized Bill | Provides detailed expense breakdown |
| Prescriptions | Supports medicines and treatment |
| Diagnostic Reports | Supports diagnosis and investigation |
| Doctor’s Advice | Supports hospitalization/treatment |
| Pharmacy Bills | Supports eligible medicine expenses |
| Bank Details | Used for eligible reimbursement payment |
| Additional Medical Records | May be required for claim assessment |
The insurer may request additional documents depending on the nature of treatment.
Important Documents to Collect Before Hospital Discharge
For reimbursement claims, document collection is especially important.
Before leaving the hospital, check whether you have received applicable copies of:
- Discharge summary
- Final bill
- Detailed/itemized bill
- Payment receipts
- Prescriptions
- Diagnostic reports
- Investigation reports
- Doctor’s consultation records
- Operation or procedure details where applicable
- Medicine bills
- Other treatment records
Keep digital copies wherever possible.
How to Check Health Insurance Claim Status
Many insurers provide claim tracking through official digital channels.
You may need information such as:
- Policy number
- Claim number
- Registered mobile number
- Patient details
Possible claim statuses can include:
Claim Registered: The claim has been received.
Under Review: Documents and policy conditions are being assessed.
Additional Information Required: More documents or clarification may be needed.
Approved: The claim has been approved according to applicable terms.
Processed/Settled: The eligible amount has been processed.
Terminology varies between insurers.
Why Can the Approved Claim Amount Be Lower Than the Hospital Bill?
A common misunderstanding is that the insurer will always pay the entire hospital invoice.
That is not necessarily the case.
The payable amount can be affected by:
Co-Payment
If a co-payment applies, the policyholder bears the applicable portion of the eligible claim.
Deductible
The insured may be responsible for expenses up to the applicable deductible.
Sub-Limits
Some benefits or treatments may have specific limits.
Non-Covered Expenses
Certain hospital or non-medical expenses may not be covered.
Policy Exclusions
Expenses associated with excluded treatments or circumstances may not be payable.
Available Sum Insured
Payment is also subject to available policy coverage and applicable benefits.
Common Reasons for Health Insurance Claim Problems
Claim difficulties can occur for several reasons.
Incomplete Documents
Missing bills, reports, receipts, or forms can delay processing.
Incorrect Information
Incorrect policy, medical, or claim information can create complications.
Treatment During a Waiting Period
Certain conditions may not be covered until the applicable waiting period has been completed.
Policy Exclusions
A treatment may fall under an exclusion.
Policy Not Active
Claims relating to treatment outside an applicable active coverage period may not be eligible.
Non-Disclosure or Misrepresentation
Material information should be provided accurately when purchasing insurance and submitting a claim.
Failure to Follow Claim Requirements
Insurers may specify notification, documentation, or submission procedures. Review and follow the applicable policy requirements.
Tips for a Smoother Health Insurance Claim
A few practical steps can make claim management easier.
Keep your policy information easily accessible.
For planned hospitalization, check the insurer’s current cashless hospital information beforehand.
Inform the insurer according to the required timeline.
Collect complete medical documents.
Review hospital bills before leaving.
Keep copies of everything submitted.
Track your claim through official channels.
Respond promptly if additional documents are requested.
Most importantly, understand the policy before an emergency occurs rather than reading it for the first time during hospitalization.
What to Check Before Buying Health Insurance for Easier Claims
Claim experience starts with choosing an appropriate policy.
Before buying, review:
- Sum insured
- Waiting periods
- Co-payment
- Deductibles
- Room-rent conditions
- Sub-limits
- Exclusions
- Cashless hospital availability
- Claim procedure
- Pre-authorization requirements
- Reimbursement procedure
- Required documents
Do not choose a policy based only on the lowest premium.
Frequently Asked Questions (FAQ)
1. How do I claim health insurance?
Inform the insurer or claims administrator, check your policy conditions, choose the applicable cashless or reimbursement route, provide the required documents, and follow the insurer’s claim procedure.
2. What documents are required for a health insurance claim?
Common documents can include the claim form, discharge summary, hospital bills, payment receipts, prescriptions, diagnostic reports, medical records, and bank details for reimbursement. Requirements vary.
3. What is a cashless health insurance claim?
It is a claim method where eligible expenses are settled directly with an eligible hospital under the applicable cashless arrangement, subject to authorization and policy terms.
4. What is a reimbursement claim?
Under reimbursement, the insured generally pays the hospital expenses first and later submits the required documents for assessment and reimbursement of eligible expenses.
5. Can I claim health insurance at any hospital?
Coverage and claim options depend on policy terms. Cashless facilities are subject to applicable hospital arrangements, while reimbursement conditions should be checked in the policy.
6. Does cashless treatment mean I pay nothing?
No. You may still have to pay non-covered expenses, deductibles, co-payments, excluded charges, or amounts beyond applicable limits.
7. How long does a health insurance claim take?
Processing time varies based on claim type, completeness of documents, medical review, insurer procedures, and applicable regulatory or policy requirements.
8. Can a health insurance claim require additional documents?
Yes. Additional medical records, reports, bills, or clarification may be requested during assessment.
9. Why is my claim amount lower than my hospital bill?
The difference may result from co-payment, deductibles, exclusions, non-payable expenses, sub-limits, available sum insured, or other policy conditions.
10. How can I track my health insurance claim?
Use the insurer’s official website, app, claims portal, helpline, or other approved channel using your claim or policy details.
Conclusion
Understanding how to claim health insurance can make it easier to manage medical expenses during hospitalization. The first step is to understand your policy, check whether the treatment is covered, and inform the insurer or claims administrator according to the required procedure.
For a cashless claim, verify the applicable hospital facility, complete the pre-authorization process, and coordinate with the hospital’s insurance desk. For reimbursement, pay the required expenses, collect complete medical and billing documents, fill out the claim form accurately, and submit everything within the applicable timeline.
Keep your discharge summary, hospital bills, payment receipts, prescriptions, diagnostic reports, and other relevant medical records organized. Missing or inaccurate information can delay claim assessment.
Also remember that the total hospital bill and the approved insurance amount may not always be the same. Co-payment, deductibles, sub-limits, exclusions, non-payable expenses, waiting periods, and available sum insured can affect the final amount.
Knowing your health insurance claim process before you need medical treatment can help you make informed decisions and avoid unnecessary confusion during an already stressful situation.
Disclaimer: This article is for general informational and educational purposes only and does not constitute insurance, medical, financial, or legal advice. Claim procedures, documentation requirements, cashless arrangements, timelines, coverage, waiting periods, exclusions, co-payments, deductibles, and settlement conditions vary by insurer and policy and may change. Always refer to your latest policy wording and contact your insurer or authorized claims administrator for claim-specific requirements.